 Reynand Wu
In the competitive landscape of e-commerce, businesses often rely on key performance indicators (KPIs) to guide their strategic decisions. Among the most frequently cited is gross margin, a metric that reflects the profitability of a product after accounting for its direct costs of production. However, a closer examination reveals that while gross margin provides a foundational understanding of product cost, it often presents an incomplete and potentially misleading picture of true profitability. E-commerce owners who solely prioritize gross margin risk overlooking significant opportunities and inadvertently eroding their bottom line. This article delves into why contribution margin offers a more accurate and actionable metric for driving sustainable e-commerce success, supported by industry insights and analytical breakdowns.
The Fallacy of Gross Margin as a Sole Indicator
Gross margin, calculated as (Revenue – Cost of Goods Sold) / Revenue, essentially tells a business what it costs to manufacture a product and deliver it to its warehouse. While this is a crucial starting point, it stops short of encompassing the full spectrum of expenses associated with bringing that product to a customer’s doorstep. Absent from this calculation are a multitude of variable costs that directly impact the profitability of each sale. These include, but are not limited to, customer acquisition costs (CAC), shipping and handling fees for outbound deliveries, packaging materials, credit card processing fees, returns and associated restocking costs, and any other direct expenses incurred in the sales and fulfillment process.
When e-commerce businesses exclusively focus on gross margin, they are essentially working with an averaged-out figure across all products and sales channels. This average can obscure the reality that certain products, despite a seemingly healthy gross margin, might be significantly less profitable due to higher associated variable costs. Consequently, decisions regarding product prioritization, marketing campaign allocation, and resource deployment can be misguided, leading to suboptimal financial outcomes.
Understanding Contribution Margin: The Metric That Truly Matters
In contrast to gross margin, contribution margin provides a more comprehensive view of profitability by accounting for all variable costs. It answers the critical question: "After all direct selling and fulfillment expenses are paid, how much revenue from this product sale is available to cover overhead and generate net profit?"
The formula for contribution margin per unit is:
Contribution Margin Per Unit = Selling Price Per Unit – Total Variable Costs Per Unit

And for contribution margin percentage:
*Contribution Margin Percentage = (Contribution Margin Per Unit / Selling Price Per Unit) 100**
This metric is invaluable because it directly reflects the profit generated by each individual sale before fixed costs are considered. By focusing on contribution margin, businesses can make more informed decisions about which products to promote, which sales channels are most effective, and how to structure pricing and discount strategies.
A Real-World Illustration: The Bells of Steel Example
To illustrate the critical difference between gross margin and contribution margin, consider a hypothetical scenario involving "Bells of Steel," a company specializing in home gym equipment. For illustrative purposes, let’s examine two products, both priced at $400: a Workout Bench and a High-End Barbell.
Product A: Workout Bench
- Selling Price: $400
- Cost of Goods Sold (COGS): $160
- Gross Margin: $240 (60%)
Based on gross margin alone, the Workout Bench appears to be the more profitable product, leaving $240 per sale before other expenses.
Product B: High-End Barbell
- Selling Price: $400
- COGS: $200
- Gross Margin: $200 (50%)
The High-End Barbell, with a lower gross margin of $200, might be deprioritized in promotional efforts.

However, when we introduce variable costs associated with selling and delivering each product, the picture dramatically shifts. These variable costs can include shipping, marketing spend (which can vary based on product complexity and target audience), packaging, and transaction fees.
Let’s assume the following variable costs for each product:
Workout Bench (Variable Costs Breakdown):
- COGS: $160
- Shipping & Packaging: $50
- Marketing/Customer Acquisition Cost (CAC): $30
- Payment Processing Fees: $8
- Total Variable Costs: $248
- Contribution Margin: $400 (Selling Price) – $248 (Total Variable Costs) = $152 (38%)
High-End Barbell (Variable Costs Breakdown):
- COGS: $200
- Shipping & Packaging: $40
- Marketing/Customer Acquisition Cost (CAC): $20
- Payment Processing Fees: $8
- Total Variable Costs: $268
- Contribution Margin: $400 (Selling Price) – $268 (Total Variable Costs) = $132 (33%)
While the Workout Bench still holds a higher gross margin, the High-End Barbell, despite its lower gross margin, generates a higher contribution margin per unit ($152 vs. $132) after accounting for all variable costs. This implies that for every sale of the Workout Bench, $152 is available to cover fixed overhead and contribute to profit, whereas for the High-End Barbell, $132 is available. In this adjusted scenario, the initial assessment would need to be re-evaluated, potentially leading to a strategic shift in how these products are marketed and promoted.
The original text presented a hypothetical where the barbell had a higher contribution margin. Let’s re-examine that scenario with more detailed variable costs to understand the potential magnitude of such a discrepancy.
Revised Hypothetical Scenario for Bells of Steel:
Let’s assume the following detailed variable costs:
Product A: Workout Bench

- Selling Price: $400
- COGS: $160
- Gross Margin: $240 (60%)
- Shipping & Packaging: $70
- Marketing/CAC (higher due to broader appeal): $40
- Payment Processing Fees: $8
- Returns/Refurbishment: $5
- Total Variable Costs: $70 + $40 + $8 + $5 + $160 (COGS) = $283
- Contribution Margin: $400 – $283 = $117 (29.25%)
Product B: High-End Barbell
- Selling Price: $400
- COGS: $200
- Gross Margin: $200 (50%)
- Shipping & Packaging (lower due to more compact nature): $40
- Marketing/CAC (more targeted, potentially higher per conversion but lower overall): $30
- Payment Processing Fees: $8
- Returns/Refurbishment (lower likelihood): $2
- Total Variable Costs: $40 + $30 + $8 + $2 + $200 (COGS) = $280
- Contribution Margin: $400 – $280 = $120 (30%)
In this revised hypothetical, the High-End Barbell, despite its lower gross margin, has a slightly higher contribution margin per unit ($120 vs. $117). This difference of $3 per sale might seem small, but when multiplied across thousands of units, it can significantly impact overall profitability. This illustrates how focusing solely on gross margin can lead businesses to misallocate resources, potentially promoting products that, while appearing profitable on the surface, contribute less to the company’s overall financial health after all direct costs are factored in.
The Implications for Discount Strategies and Promotional Periods
The disconnect between gross margin and contribution margin also profoundly affects how businesses approach discounts and major promotional events like Black Friday.
Consider a scenario with "podcast gloves" selling for $100.
- Gross Margin: 80% ($80 per sale)
- Contribution Margin: 40% ($40 per sale)
If a business runs a 20% off sale, the discount is $20. Many might assume this means they are only sacrificing $20 of their $80 gross profit, leaving $60. However, this is a critical miscalculation. The discount directly reduces the revenue available after variable costs are paid.
The $20 discount does not come off the gross margin; it comes directly out of the contribution margin. In this case:
- Original Contribution Margin: $40
- New Contribution Margin after 20% discount: $40 – $20 = $20
This means a seemingly modest 20% discount has effectively halved the real profit generated by that sale. If the promotional period also necessitated increased advertising spend to drive traffic, the situation becomes even more detrimental, as additional variable costs further erode the already diminished contribution margin.
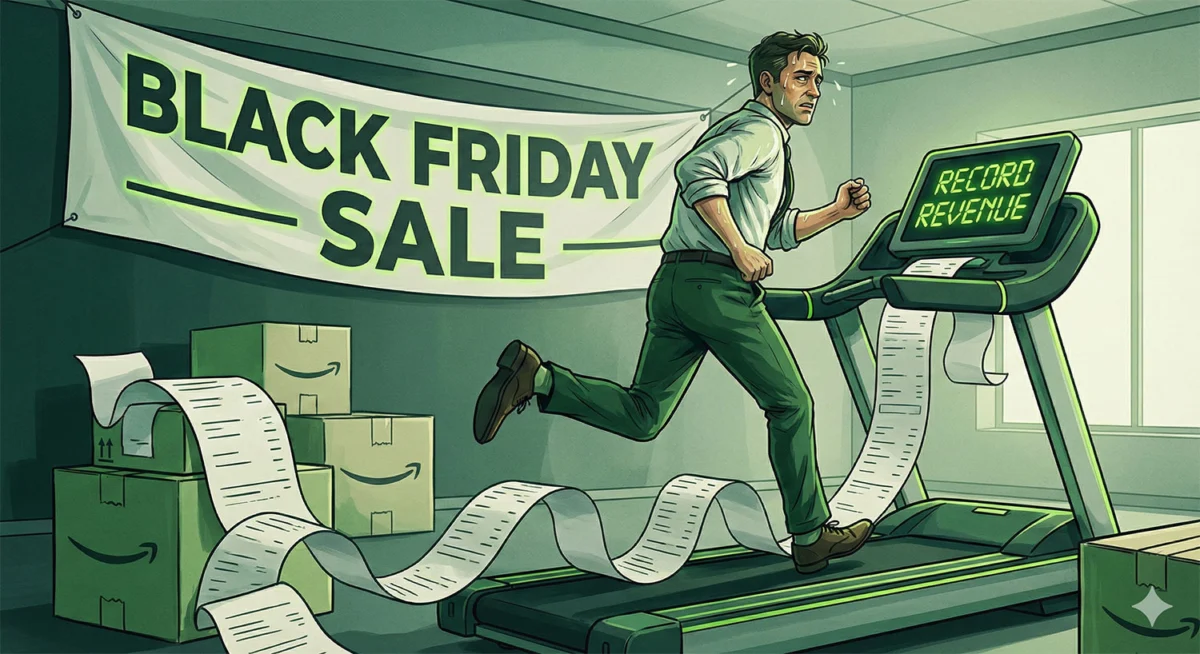
This explains why many e-commerce businesses report record revenue during peak sales periods like Black Friday but see a disproportionately smaller increase in net profit. They are essentially working harder, investing more in marketing and operations, to sell more units at a significantly reduced real margin. The treadmill effect is palpable: immense effort yields only incremental financial gains, leaving owners feeling exhausted and questioning the true return on their promotional investments.

Calculating Your Contribution Margin: A Practical Guide
Since contribution margin is not a standard line item on most Profit and Loss (P&L) statements, businesses must calculate it themselves, typically using spreadsheet software. The process involves meticulously identifying and summing all variable costs associated with each product and sales channel.
Key Variable Costs to Include:
- Cost of Goods Sold (COGS): The direct cost of manufacturing or acquiring the product.
- Shipping and Handling: Costs associated with packaging and transporting the product to the customer.
- Payment Processing Fees: Transaction fees charged by credit card companies and payment gateways.
- Customer Acquisition Cost (CAC): Expenses related to marketing and advertising that directly lead to a sale (e.g., ad spend, affiliate commissions, influencer marketing). This can be tricky to allocate per product and may require channel-specific analysis.
- Packaging Materials: Costs of boxes, tape, labels, and any protective materials.
- Returns and Allowances: Estimated costs associated with product returns, including return shipping, restocking, and potential product damage.
- Sales Commissions: If applicable, commissions paid to sales representatives.
- Fulfillment Costs: Fees charged by third-party logistics (3PL) providers for warehousing, picking, packing, and shipping.
By accurately calculating the contribution margin for each product and sales channel, businesses gain a clear understanding of their true profitability drivers. This allows for more strategic decision-making, enabling them to:
- Prioritize High-Contribution Products: Focus marketing efforts and inventory on products that generate the most profit after all direct costs are accounted for.
- Optimize Pricing Strategies: Understand the impact of price adjustments on contribution margin and overall profitability.
- Refine Discounting and Promotions: Make informed decisions about the true cost of discounts, ensuring they do not excessively erode profit margins.
- Evaluate Sales Channels: Identify which channels are most effective in delivering profitable sales, considering the variable costs associated with each.
- Improve Operational Efficiency: Identify areas where variable costs can be reduced without compromising customer experience.
Your Assignment This Week
To truly harness the power of contribution margin, it is essential to conduct a thorough analysis within your own business. This week, dedicate time to calculate the contribution margin for your top-selling products and your primary sales channels. You may find that products you believed were your strongest performers are, in fact, lagging behind others once all variable costs are considered. Conversely, channels you may have overlooked could be your most profitable. This exercise is not merely an academic one; it is a fundamental step toward achieving robust financial mastery and ensuring the long-term sustainability of your e-commerce enterprise. By shifting your focus from the superficial glow of gross margin to the concrete reality of contribution margin, you unlock a more accurate path to understanding and maximizing your business’s true profitability.

 Nana
 Dwi Wanna