 Suro Senen
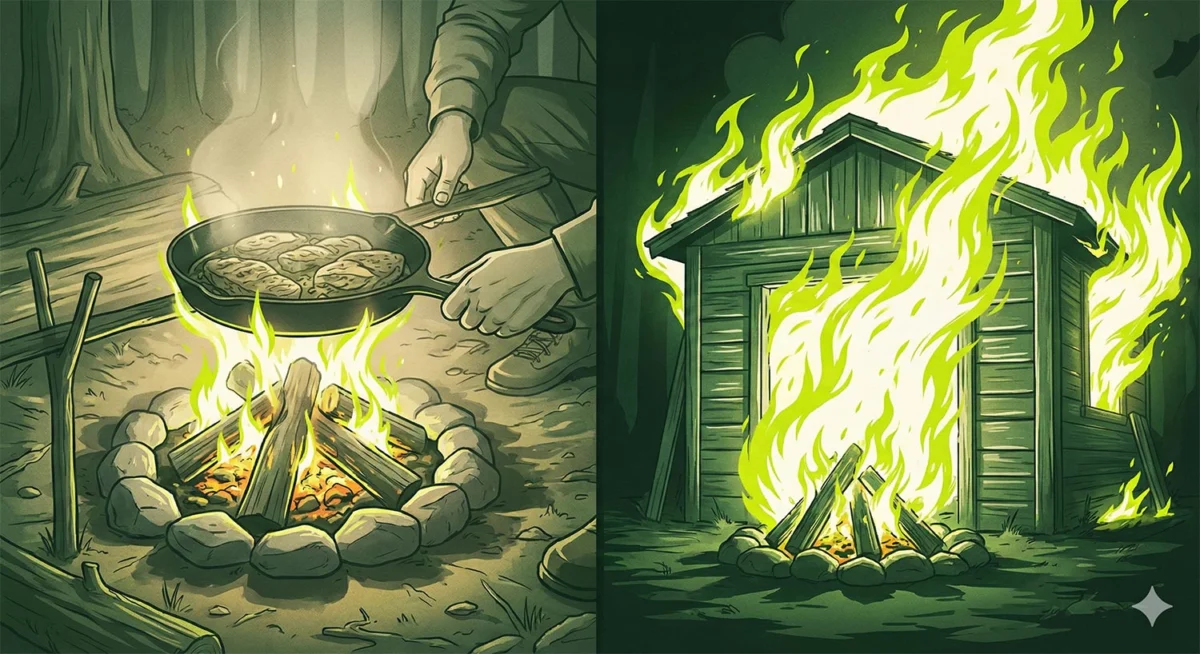
A routine day in a parking lot turned into a stark lesson in financial vulnerability for Bill, a business partner whose hands trembled as he clutched a letter. The communication, from a primary supplier responsible for a significant 80% of the inventory for a joint venture, announced an immediate termination of their relationship. For Bill, this wasn’t just a business setback; it was a direct threat to his personal finances. He held a seven-figure personal guarantee for the business’s debts. In the event of the company’s collapse, the bank would not be limited to pursuing the limited liability company’s assets; they would have the legal recourse to seize Bill’s personal assets, including his home, brokerage accounts, and savings. This harrowing 20-minute ordeal, though ultimately stemming from a clerical error, served as a potent reminder of how quickly financial leverage can transform into a devastating liability.
This incident, though resolved, underscores a critical issue for entrepreneurs across various sectors, particularly in the fast-paced world of e-commerce. Over nearly two decades, the author has witnessed debt acting as both a catalyst for unprecedented business growth and, conversely, a destructive force that has led to financial ruin for many. The individuals most affected are often not lacking in intelligence or business acumen, but rather are caught in the whirlwind of rapid expansion, making quick decisions to access capital when immediate needs arise. The critical oversight, however, lies in a failure to fully comprehend the intricate terms of debt, meticulously model cash flow projections, or adequately prepare for potential adverse scenarios.
In response to this recurring pattern of financial distress, Bill and the author convened to identify and analyze the most common and dangerous debt-related mistakes business owners are making. Their insights offer a crucial roadmap for navigating the complexities of business financing and mitigating potential risks.
The Absence of Robust Cash Flow Forecasting Before Borrowing

A foundational error that frequently leads to financial distress is the failure to conduct thorough cash flow forecasting before incurring any debt. Experts universally recommend a minimum of a 13-week forward-looking cash flow projection. This detailed analysis should meticulously map out the precise timing of incoming payments and outgoing obligations, ensuring that debt repayment obligations can be met without jeopardizing operational solvency.
This is particularly critical when considering Merchant Cash Advances (MCAs). These financial instruments operate by deducting a fixed daily percentage of a business’s revenue. If a business has a profit margin of, for instance, 12%, and an MCA agreement dictates a 10% daily revenue deduction for repayment, the business is effectively operating on a razor-thin 2% margin for the entire duration of the repayment period. Businesses that experience collapse under such arrangements often claim they were blindsided, a consequence of not having meticulously mapped out their future financial trajectory. Any decision to borrow without a detailed model demonstrating repayment capacity and projecting business growth should be approached with extreme caution.
The Perils of Reactive, Rather Than Proactive, Financing
A significant hurdle for businesses seeking capital is the traditional banking sector’s preference for proactive engagement. Banks are often more willing to extend substantial lines of credit to businesses that are demonstrably healthy and financially stable. Conversely, when a business finds itself in a liquidity crisis, facing declining revenues and tightening cash flow, traditional banks are typically unwilling or unable to provide assistance. The approval process for conventional bank loans is often lengthy, requiring two to three years of consistent financial records, demonstrable revenue streams, and solid profit margins. This process can take 60 to 90 days and involves extensive documentation and scrutiny.
During times of financial stress, the inherent risks become more apparent to lenders, making approval highly improbable. The adage, "the best time to secure a line of credit is when you don’t need it," holds significant weight. Once a credit line is approved, many smaller facilities do not impose stringent ongoing covenants. This means that if a business secures a line of credit while performing well and later experiences a downturn, it can often still access those funds. This optionality can be a lifeline, but it necessitates establishing these financial relationships before a crisis emerges. Building rapport with local and regional banks and exploring options like SBA 7(a) loans, despite their administrative burdens, is a prudent strategy for long-term financial resilience.

Neglecting Rigorous Return on Investment (ROI) Tracking
Another common pitfall is the failure to meticulously track the return on investment for borrowed funds. A recent anecdote from the e-commerce community highlighted a business owner who secured a six-figure EIDL loan during the COVID-19 pandemic, primarily due to its low interest rate. However, 18 months later, the owner could not account for the specific use or impact of these funds, leaving them in a precarious financial position when repayment became due. This oversight is easily made when a substantial influx of capital appears, potentially diminishing financial discipline.
Every borrowed dollar must have a clearly defined purpose, a projected return, and a rigorous tracking mechanism to measure actual returns against projections. If borrowed funds are not immediately deployed into revenue-generating activities, they should at the very least be held in a separate, high-yield savings account. Intentionality in every drawdown and obsessive tracking of returns are essential to ensure that debt contributes positively to business growth.
Underestimating the Implications of Personal Guarantees
The incident involving Bill serves as a stark reminder of the profound personal risk associated with personal guarantees. A personal guarantee allows creditors, in the event of business default, to bypass the corporate veil and pursue an individual’s personal assets. This includes homes, investment portfolios, and savings, with limited exceptions typically for retirement accounts. Before signing a personal guarantee, business owners must ask themselves if they would be willing to transfer the equivalent amount from their personal savings into the business with no expectation of repayment. Functionally, signing a personal guarantee means precisely that.

Furthermore, many business owners underestimate the personal guarantees embedded within seemingly innocuous business credit cards. Popular options like the American Express Gold, Chase Ink, and Capital One Spark cards often come with personal guarantees. The short-term financial float gained from these cards for rewards purposes can transform into significant personal debt if the business fails. A comprehensive audit of all personal guarantee exposures across all financial instruments—credit cards, term loans, lines of credit, and equipment financing—is crucial. Summing these liabilities and assessing the personal capacity to meet such an obligation is a vital risk management step.
Utilizing Debt to Mask a Fundamentally Flawed Business Model
A critical indicator of underlying business problems is the need to borrow capital to fund subsequent inventory purchases. If a business’s recent inventory sales do not generate sufficient cash to cover the next purchase order, it signals a fundamental issue that debt cannot resolve. This could stem from excessively thin profit margins, unsustainable customer acquisition costs (CAC), bloated operational expenses, significant amounts of dead stock tying up capital, or excessive owner draws.
While taking on debt to acquire more inventory might appear to be a solution, it is merely a temporary deferral of the problem. It effectively kicks the can down the road, leaving the business in a more precarious position when the underlying issues are eventually confronted, compounded by existing debt obligations. Addressing and rectifying the core business model—improving margins, optimizing marketing spend, controlling expenses, and managing inventory effectively—must precede any consideration of further borrowing. Debt will only amplify the problems of a fundamentally unsound business.
Miscalculating the True Cost of Capital

A prevalent and dangerous miscalculation involves the true cost of capital, particularly with instruments like Merchant Cash Advances. A stated "10% fee" on an MCA is not equivalent to a 10% interest rate. The mathematical structure of these agreements is often intentionally designed to be misleading. For example, borrowing $100,000 and agreeing to repay $110,000 is presented as a "10% fee." This can lead an owner to believe the rate is comparable to credit cards. However, this is a gross misrepresentation.
A 10% annual interest rate means paying $10,000 to borrow $100,000 for an entire year. MCAs, conversely, demand repayment within a much shorter timeframe, typically 10 to 20 weeks. If $110,000 is repaid over 10 weeks, the effective annual percentage rate (APR) can soar to 50% or higher. The issue is compounded by the fact that early payments are made on funds that have only been utilized for a fraction of the total repayment period. The money repaid in the first week, for instance, was borrowed for only seven days, yet a portion of the 10% "fee" is applied. This can push the true APR into the 75-100% range, and sometimes even higher.
While MCAs are not inherently malicious and can serve a purpose for rapidly growing businesses needing to finance inventory for proven products, they are frequently misused. Many owners resort to MCAs to bridge cash flow gaps or mask underlying margin problems, unknowingly incurring astronomical interest rates. Tools like Bill’s free APR calculator are invaluable for accurately assessing the true cost of capital before committing to such agreements.
The Downward Spiral of Stacking Loans
A particularly destructive financial strategy is "stacking" loans, which involves using one debt instrument, such as an MCA, to pay off another. This practice creates a vicious cycle where each new loan comes with a higher interest rate, provides a shorter repayment runway, and exacerbates the existing financial hole. Instances have been observed where business owners juggle three or four MCAs simultaneously, with daily deductions from revenue gradually, and then rapidly, strangling the business’s cash flow.

While refinancing expensive, short-term debt with more affordable, long-term debt can be a sound strategy—for example, replacing an MCA with a 5-year term loan—this is contingent on the business being healthy enough to qualify. This condition is rarely met once a business has fallen into the debt-stacking spiral. At this point, restructuring and operational reform, rather than additional financing, become the imperative.
Challenging the Belief That Debt Is the Sole Option
While e-commerce businesses, with their significant inventory requirements, often necessitate more working capital than service-based industries, heavy reliance on debt is not an immutable reality. A well-managed business can mitigate its financing needs. Higher profit margins reduce the reliance on external capital. Faster inventory turnover liberates cash flow. Negotiating favorable supplier terms extends payment runways. Organic growth, fueled by effective marketing strategies, can often be self-sustaining without the need for debt to fund advertising.
In many situations, the more prudent course of action involves making difficult strategic decisions. This might include accepting slower growth, implementing stringent cost-cutting measures, or discontinuing underperforming product lines. These choices, while potentially uncomfortable in the short term, foster a business that is financially independent and built on a solid foundation, even if its scale is more modest.
Resources for Further Financial Education

For business owners seeking to deepen their understanding of debt management and financial prudence, several resources are invaluable. Mehtab Bhogal has authored comprehensive articles on this subject, and Bill’s true APR calculator provides a critical tool for demystifying the actual cost of various financing options.
For those interested in ongoing insights into financial mastery and avoiding common pitfalls that derail seven-figure businesses, engaging with communities of experienced e-commerce owners can provide invaluable guidance. Regular updates and shared experiences from entrepreneurs who have successfully navigated these complex financial waters offer a powerful network for learning and growth.

 Basiran
 Jia Lissa