 Basiran
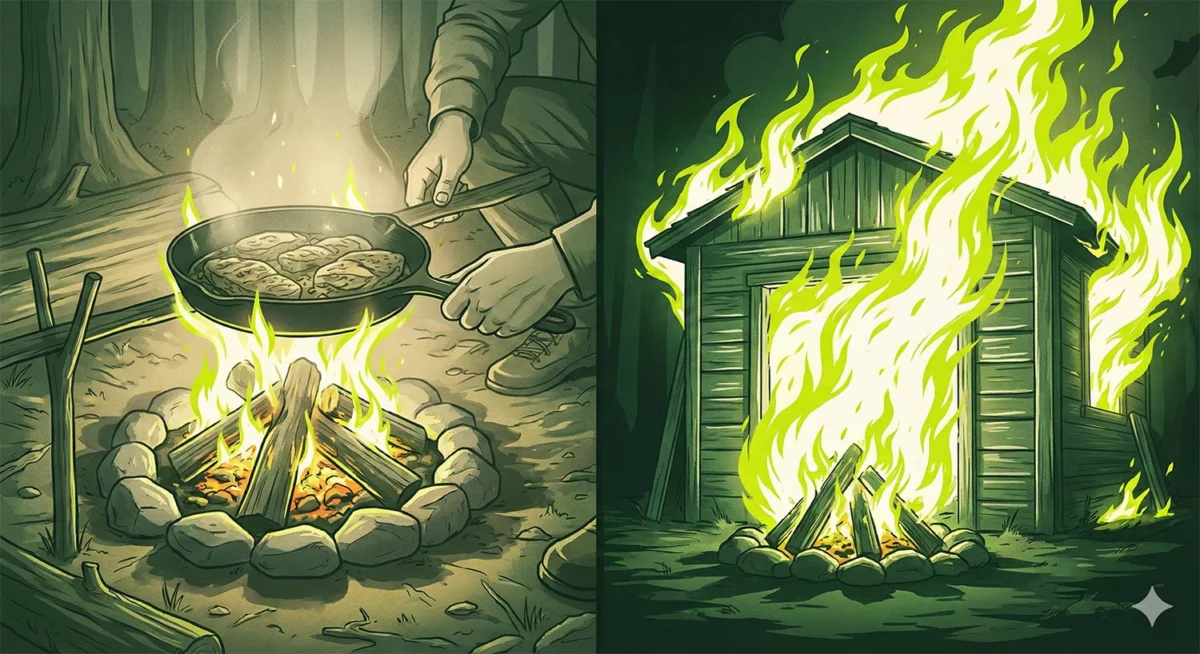
A chilling incident involving a seven-figure personal guarantee and a sudden supplier termination served as a stark wake-up call for e-commerce entrepreneurs, highlighting the razor-thin line between debt as a growth engine and a destructive force. This near-catastrophe, stemming from what was later revealed to be a clerical error, underscores a pervasive issue within the fast-paced world of online retail: the dangerous underestimation of debt’s complexities and potential pitfalls. The experience has prompted a deeper examination of common financial missteps that can lead even seemingly robust businesses toward financial ruin.
The incident, which unfolded in a quiet parking lot, saw entrepreneur Bill, his hands visibly trembling, confronting a letter that threatened the very foundation of a significant business investment he shared with a colleague. The communication, purportedly from their primary supplier—responsible for a staggering 80% of the business’s Stock Keeping Units (SKUs)—declared an immediate termination of their relationship. For Bill, this wasn’t just a business setback; it was a personal crisis. He was personally liable for a seven-figure debt associated with the venture. In the event of the business’s collapse, creditors would not be limited to seizing company assets; they would have the legal recourse to pursue Bill’s personal assets, including his home, brokerage accounts, and savings.
"If the company went under, the bank wasn’t coming for the LLC. They were coming for Bill," a source close to the situation recounted, emphasizing the gravity of personal guarantees in business financing.
Fortunately, the dire pronouncement proved to be a temporary scare, a clerical oversight that was quickly rectified with a simple "Sorry, disregard." However, the mere twenty minutes of intense anxiety and fear had a profound and lasting impact. The experience aged Bill perceptibly and seared into the minds of both him and his partner the acute awareness of how swiftly debt can transform from a strategic tool into an existential threat. This harrowing episode has illuminated the critical need for e-commerce business owners to approach debt with a level of caution and diligence that often seems to be overlooked in the pursuit of rapid growth.

The Allure and Danger of E-commerce Debt
Over nearly two decades immersed in the e-commerce landscape, the author of the original account has witnessed firsthand the dual nature of debt. It has been instrumental in building empires, propelling businesses to unprecedented heights, yet it has also been the architect of personal and financial devastation, sometimes within the same fiscal year. The entrepreneurs who find themselves in precarious debt situations are rarely lacking in intelligence or ambition. More often, they are driven individuals, consumed by the relentless demands of a growing business. The ease with which financing options are presented and the immediate need for capital often lead them to click "accept" without fully comprehending the long-term implications.
What frequently gets lost in the urgency is a thorough understanding of the loan’s terms, a meticulous modeling of future cash flow, and a comprehensive assessment of potential worst-case scenarios. It is this gap in due diligence that the recent experience with Bill and his partner aimed to address. They identified several recurring and particularly perilous debt-related mistakes that are plaguing the e-commerce sector.
Critical Debt Missteps in E-commerce
The Absence of Robust Cashflow Forecasting Before Borrowing
A fundamental requirement before engaging with any form of debt is the creation of a forward-looking cashflow forecast, ideally spanning at least 13 weeks. This forecast must meticulously detail the timing of all incoming payments and outgoing expenses, ensuring a clear picture of the business’s ability to meet its financial obligations. This is particularly crucial when considering Merchant Cash Advances (MCAs). MCAs operate by deducting a daily percentage of a business’s revenue. If a business has a profit margin of, for example, 12%, and an MCA is drawing 10% of daily revenue, the business is effectively operating on a mere 2% margin for the entire duration of the repayment period.

Businesses that succumb to the pressures of MCAs often do so because they failed to anticipate the impact of these daily deductions on their future liquidity. Without a detailed financial model that illustrates how the borrowed funds will be repaid and, more importantly, how they will contribute to business growth, accepting such financing is a gamble with potentially catastrophic odds.
Reactive Financing: A Recipe for Disaster
The traditional banking sector often exemplifies the pitfalls of reactive financing. Banks are generally more inclined to extend substantial lines of credit to businesses that are already performing well, exhibiting consistent revenue growth and healthy profit margins over several years. The approval process with conventional banks is notoriously lengthy, often taking 60 to 90 days, and involves extensive documentation and rigorous scrutiny of financial health.
Conversely, when a business finds itself in a crisis—experiencing declining revenues, shrinking margins, or severe cash flow constraints—it is precisely at this moment that traditional banks are least likely to offer assistance. The signs of financial distress are evident in the numbers, leading to automatic disqualification.
The adage, "The best time to get a line of credit is when you don’t need it," holds profound truth. Once a line of credit is approved, many smaller facilities do not impose stringent ongoing covenants. This means that if a business secures such a line while it is financially healthy, it can potentially draw upon it even if its fortunes later decline. This strategic foresight provides invaluable optionality, a lifeline that can save businesses during turbulent times. Therefore, cultivating relationships with local and regional banks, and exploring options like SBA 7(a) loans, even when the process is cumbersome, is a proactive measure that can yield significant long-term benefits.
Neglecting Rigorous Return on Investment (ROI) Tracking
A concerning trend within the e-commerce community involves the acceptance of loans, such as the EIDL loans offered during the COVID-19 pandemic, based primarily on attractive interest rates, without a clear plan for their utilization or a method for tracking their effectiveness. A member of an e-commerce forum shared a story of securing a six-figure EIDL loan, only to find 18 months later that the purpose and impact of the funds remained unclear. This ambiguity often leads to significant repayment challenges.

The influx of substantial capital can easily erode financial discipline. Every borrowed dollar should have a clearly defined purpose, a projected return, and a system for rigorously tracking its actual performance against those projections. If borrowed funds are not immediately deployed into revenue-generating activities, they should at the very least be placed in a separate, interest-bearing account. Intentionality in every drawdown and obsessive tracking of returns are essential safeguards against squandered capital.
The Underestimation of Personal Guarantees
Returning to the harrowing experience of Bill, the concept of a personal guarantee (PG) is perhaps the most acutely dangerous aspect of business debt for entrepreneurs. A PG effectively obliterates the legal separation between a business and its owner. If the business defaults on its obligations, creditors can pursue the owner’s personal assets—their home, savings, and investments—beyond any company assets.
Before signing a personal guarantee, business owners must engage in a critical self-assessment: "Would I willingly transfer this exact amount of money from my personal savings into this business today, fully accepting that I might never see it again?" In essence, signing a PG signifies precisely this level of commitment.
A frequently overlooked aspect of personal guarantees lies with business credit cards. Many popular business credit cards, including well-known options from American Express, Chase, and Capital One, carry personal guarantees. The points accumulated and the short-term float offered for cashback rewards can mask the underlying personal liability. If the business falters, this seemingly innocuous float transforms into personal debt overnight. A comprehensive audit of all outstanding PGs across credit cards, term loans, lines of credit, and equipment financing is imperative. Understanding the aggregate personal exposure and honestly assessing one’s capacity to absorb such a financial shock is a vital step in risk management.
Using Debt to Conceal a Flawed Business Model
When a business’s latest inventory purchase cannot be funded by the cash generated from the previous batch, it signals a fundamental issue with the business model, not merely a temporary cash flow problem. This could indicate margins that are too thin, customer acquisition costs (CAC) that are excessively high, bloated operational expenses, significant amounts of unsellable or obsolete inventory, or excessive owner draws.

While borrowing to acquire more inventory might seem like an immediate solution, it often merely postpones the inevitable confrontation with the underlying problems. The business is effectively kicking the can down the road, accumulating debt while the core issues remain unaddressed. The recommended approach is to first diagnose and rectify the systemic flaws within the business model. Relying on debt to mask these issues will only compound the problems, leading to a more severe crisis when the debt burden becomes insurmountable.
Miscalculating the True Cost of Capital
The stated fees on financial instruments like Merchant Cash Advances (MCAs) can be highly deceptive. A "10% fee" on an MCA is not equivalent to a 10% annual interest rate. The mathematical structure of these agreements is often designed to obfuscate the true cost of capital.
For instance, borrowing $100,000 and agreeing to repay $110,000 is presented as a "10% fee." A business owner might interpret this as a relatively low interest rate, comparable to or even lower than credit card rates. However, MCAs typically demand repayment within a much shorter timeframe, often 10 to 20 weeks, not a full year. When the repayment period is compressed, the effective Annual Percentage Rate (APR) can skyrocket. A repayment of $110,000 over just 10 weeks on a $100,000 principal means that the full interest amount is paid back in a little over two months. This compresses the annual cost into a fraction of the year, pushing the true APR towards 50% or even higher.
The problem is exacerbated by the daily deduction structure. The payments made in the initial weeks of the repayment period are based on money that was only borrowed for a very short duration. This means the effective interest rate on those early payments is astronomically high. When all these factors are meticulously calculated, a seemingly benign "10% fee" can translate into a true APR of 75-100% or even more.
While MCAs can serve a purpose for rapidly growing businesses that require short-term inventory financing for proven product lines, they are frequently misused by businesses attempting to bridge cash gaps or mask underlying margin issues. This often results in owners paying exorbitant interest rates without realizing the true cost. To combat this, resources like Bill’s free calculator are invaluable for accurately assessing the true APR before committing to such agreements.

The Spiral of Stacking Loans
A particularly dangerous practice is the use of one loan to pay off another, especially when it involves multiple MCAs. This creates a vicious cycle where each new loan is typically secured at a higher rate, provides less breathing room, and deepens the financial hole. Some entrepreneurs find themselves juggling three or four MCAs simultaneously, with daily deductions draining revenue and slowly, then rapidly, suffocating the business.
While refinancing expensive short-term debt with more affordable long-term debt can be a strategic move, this is contingent on the business being healthy enough to qualify for the new financing. This is rarely the case for businesses already caught in a debt spiral. When a business reaches the point of needing to stack loans, the primary requirement is restructuring and operational overhaul, not simply acquiring more debt.
The Illusion of Debt as the Sole Solution
While e-commerce businesses, particularly those dealing with inventory, inherently require more working capital than service-based industries, reliance on heavy debt is not an inevitable outcome. Operating a lean and efficient business can significantly reduce the need for external financing.
Strategies such as maintaining higher profit margins, optimizing inventory turnover to free up cash more rapidly, negotiating favorable supplier terms to extend payment runways, and fostering organic growth that doesn’t necessitate borrowing for advertising campaigns can all contribute to financial independence. In some instances, making difficult but necessary decisions, such as moderating growth expectations, implementing cost-cutting measures, or discontinuing underperforming product lines, is a more prudent approach than borrowing to avoid immediate discomfort. These actions, while challenging and perhaps slower, foster the development of a more resilient business that can stand on its own financial footing.
Resources for Navigating Debt

For those seeking to delve deeper into the complexities of e-commerce financing and debt management, several resources are highly recommended. Mehtab Bhogal’s insightful articles offer comprehensive guidance on this topic. Furthermore, Bill’s accessible true APR calculator provides a crucial tool for business owners to perform accurate financial calculations before entering into debt agreements.
The journey of building a successful e-commerce business is fraught with financial challenges. By understanding the inherent risks associated with debt and proactively implementing sound financial management practices, entrepreneurs can navigate these complexities more effectively, transforming debt from a potential threat into a carefully managed tool for sustainable growth.

 Laily UPN